Trucking Market Recovery Gains Strength From Data Centers and Retail Demand
Staff
Published November 2, 2026
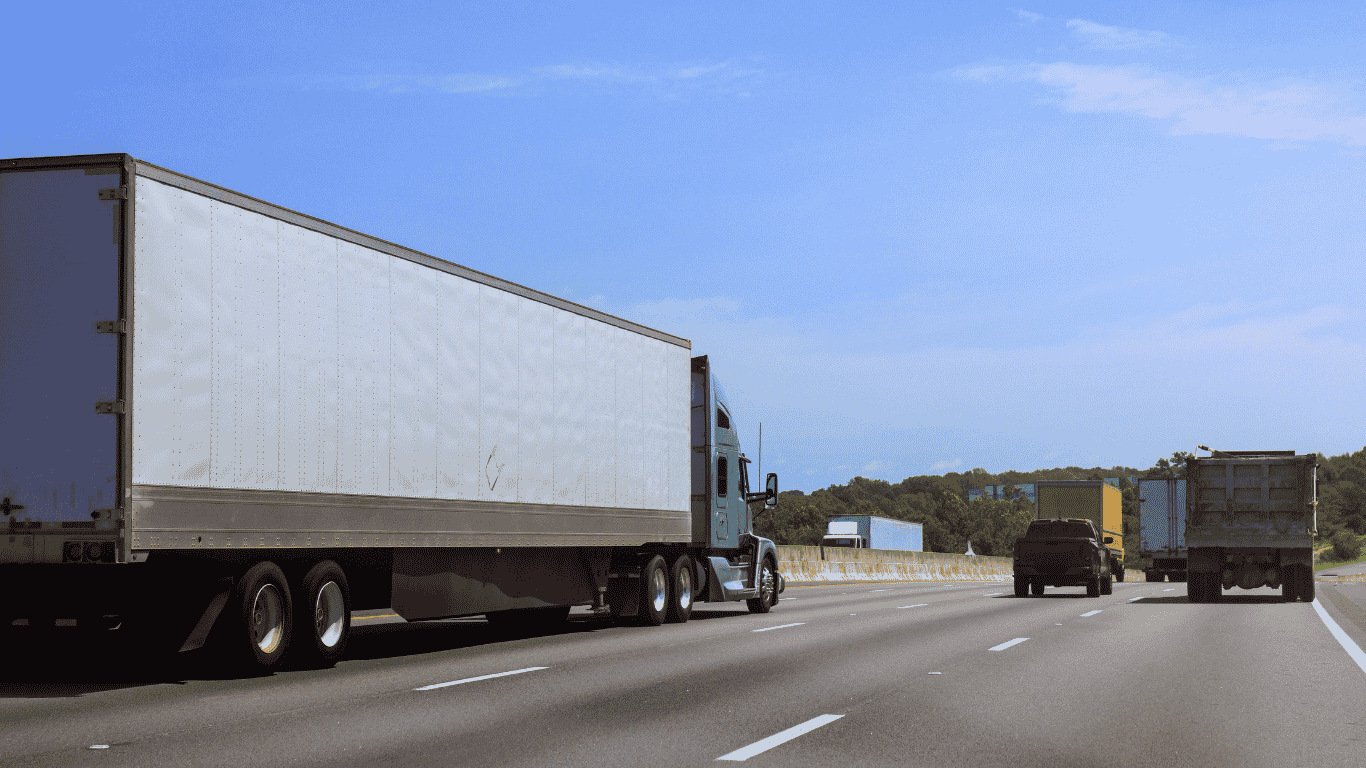
A surge in technology-related manufacturing and resilient household spending are supporting freight activity, but industry growth remains concentrated in a handful of key sectors, according to ATA Chief Economist Bob Costello.
CHARLOTTE, N.C. — Growth in domestic manufacturing, supported largely by the rapid expansion of data centers and continued consumer spending, is providing important support for the U.S. economy and the trucking industry, according to American Trucking Associations (ATA) Chief Economist Bob Costello.
Speaking about the latest freight market developments during ATA's 2026 Management Conference and Exhibition, held Oct. 17–20, Costello explained that production in the computer and electrical equipment sectors has become one of the primary drivers of manufacturing growth.
Although this increase in production has created additional freight opportunities, particularly for trucking companies transporting technology-related equipment and supplies, Costello pointed out that the broader manufacturing picture remains less encouraging.
Computer and electrical equipment manufacturing accounts for only around 10% of total U.S. manufacturing output. Without the contribution of these industries, overall manufacturing production would show virtually no growth, he explained.
Despite this concentration, the improving manufacturing environment has been an important factor behind the recent recovery in freight transportation. Several major trucking companies have reported stronger activity connected to the expanding data center market, while others have seen increased shipment volumes from manufacturing customers.
The growing demand for data center construction and related infrastructure is creating opportunities for carriers transporting electrical components, specialized equipment, building materials, and other industrial supplies. At the same time, improvements in manufacturing shipments are providing additional support to freight volumes across certain transportation segments.
However, Costello emphasized that the current recovery is fundamentally different from previous trucking market cycles.
"We are in a cycle like we have never seen before and it's all supply driven," he said.
One of the biggest factors behind this shift is the reduction in available trucking capacity. The number of carriers operating in the market has declined as some businesses have been forced into bankruptcy, while others have consolidated through mergers and acquisitions.
Additional regulatory enforcement is also affecting the availability of drivers. Stricter oversight of English language proficiency requirements, non-domiciled commercial driver's licenses (CDLs), and commercial driver training schools has introduced further limitations on the industry's driver supply.
Stay Informed
Get freight market insights delivered to your inbox
Join industry professionals receiving our weekly analysis.
These developments are gradually changing the balance between freight demand and available transportation capacity. With fewer carriers and drivers competing for shipments, companies that remain active may benefit from improved market conditions. Nevertheless, reduced capacity does not automatically translate into stronger profitability for every carrier.
Trucking businesses are also dealing with significant operating cost pressures. Elevated diesel prices, rising driver wages, maintenance expenses, insurance costs, and other operational expenditures continue to challenge profitability. Competition for a smaller pool of qualified drivers is adding further pressure, making it increasingly important for carriers to manage expenses and improve operational efficiency.
Beyond manufacturing, construction activity and consumer spending remain important sources of economic support, Costello noted. Infrastructure development, commercial construction, and household purchases continue to generate freight demand across multiple sectors.
The U.S. economy is projected to expand by 2.4% in real, inflation-adjusted gross domestic product (GDP) this year, slightly above the 2.1% growth recorded last year. This outlook suggests that economic activity remains relatively stable, even as businesses and consumers face higher costs and ongoing uncertainty.
Nevertheless, persistent inflation and elevated interest rates could create challenges for the retail industry and household consumption in the months ahead. Higher borrowing costs can influence major purchases, reduce consumer purchasing power, and slow activity in interest-sensitive sectors such as housing and automotive manufacturing.
So far, however, higher prices have not significantly weakened retail activity or freight demand from companies serving consumer markets. Recent financial reports from major less-than-truckload carriers have pointed to continued strength in retail-related shipments, suggesting that consumer demand remains an important source of support for freight transportation.
Costello also said that, despite concerns about inflation, there are currently no clear indications that the U.S. economy is heading toward a recession. Consumer spending has continued to expand despite higher prices, increasing at an annualized rate of 3.8% in September.
This resilience is particularly important for trucking because consumer purchases directly influence freight volumes across a wide range of industries, including retail, food and beverages, household goods, and other essential products. As long as consumers continue spending, transportation companies are likely to benefit from a relatively steady flow of shipments.
Schneider National President and CEO Jim Filter also addressed the strength of consumer demand during the company's latest earnings call. He acknowledged that household spending has remained relatively resilient but cautioned that inflation and affordability concerns could eventually create additional pressure on certain markets.
"Higher interest rates and affordability constraints continue to weigh on certain key markets such as housing and automotive," Filter said.
He also explained that the company's third-quarter freight volumes followed normal seasonal patterns and typical inventory trends, rather than reflecting a broader deterioration in customer demand.
For the trucking industry, these developments point to a market that is gradually stabilizing but remains uneven. Data center investments, manufacturing activity, construction projects, and consumer spending are currently providing much of the support for freight demand, while capacity reductions are helping reshape the competitive landscape.
The coming months will be important in determining whether these sources of demand can sustain the recovery. At the same time, carriers will need to navigate fuel price volatility, labor expenses, regulatory changes, and the possibility of slower consumer activity.
Although the current environment offers opportunities for some transportation companies, a broader and more balanced recovery will likely depend on stronger growth across additional manufacturing and industrial sectors.