Holiday Shipping Season Could Drive Trucking Rates Even Higher
Staff
Published November 11, 2026
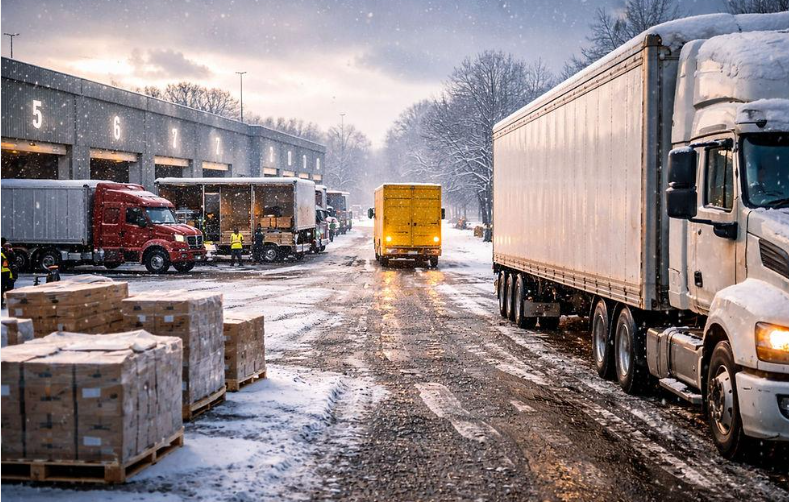
Freight demand remains relatively weak, but shrinking truck availability is giving carriers greater negotiating power. With the holiday shipping season underway, tightening capacity could push transportation rates even higher.
The U.S. trucking market is showing signs of a shift in carriers' favor. Although freight volumes remain below last year's levels, truckload operators are benefiting from higher spot rates and improved negotiating power as available capacity continues to shrink.
The latest market figures suggest that the industry does not need a major increase in freight demand to experience tighter conditions. A declining number of available trucks, combined with seasonal shipping activity, is creating an environment in which carriers have more control over pricing.
According to DAT Freight & Analytics, the national average dry van spot rate reached $3.05 per mile in October, marking its highest monthly average since February 2022.
That represented a 4-cent increase from September and a significant 98-cent jump compared with October 2025.
Refrigerated and flatbed rates also remained substantially above year-earlier levels, although neither equipment category recorded a monthly increase in October.
October's average spot rates were as follows:
Dry Van: $3.05 per mile, up 4 cents from September and 98 cents year over year.
Refrigerated (Reefer): $3.60 per mile, down 2 cents month over month but up $1.12 year over year.
Flatbed: $3.61 per mile, unchanged from September and up $1.10 compared with October 2025.
These figures highlight a notable change in the freight market. Even without a broad-based recovery in shipping demand, trucking rates have climbed considerably, largely because fewer trucks are available to handle incoming loads.
Higher Freight Rates Despite Sluggish Shipping Demand
The recent increase in spot rates is not the result of a significant freight boom. Instead, the market appears to be experiencing a growing imbalance between available trucking capacity and shipping requirements.
DAT's Truckload Volume Index showed relatively little movement in October compared with September. More importantly, freight volumes remained below year-earlier levels across all three major equipment categories.
Dry van volumes declined 2% year over year, refrigerated freight fell 9%, and flatbed volumes dropped 7%.
At the same time, the number of trucks listed as available on DAT One was approximately 22% to 26% lower than a year earlier, depending on equipment type.
This difference between freight demand and available capacity helps explain why carriers are gaining leverage despite relatively weak shipping activity.
"Brokers moved fewer loads than a year ago and paid carriers about a dollar a mile more to move them last month," said Dean Croke, DAT's principal industry analyst.
He also pointed out that elevated fuel prices and other operating expenses remain a challenge, but carriers are entering the holiday freight season in a stronger position to choose their loads and negotiate more favorable rates.
For trucking companies, this represents an important development. After an extended period of challenging market conditions, fewer available trucks can improve pricing opportunities, particularly for carriers that maintain reliable equipment, consistent service, and the flexibility to handle changing freight requirements.
Holiday Freight Demand Could Tighten Capacity Further
More recent market indicators suggest that trucking capacity remains under pressure as the industry moves deeper into the holiday shipping season.
According to the Nov. 9 market update from third-party logistics provider TRAFFIX, spot rates have remained relatively stable over the previous two months. However, carriers continue to have greater flexibility when deciding which loads to accept.
One important indicator of this shift is the tender rejection rate. This metric measures how frequently carriers decline freight offered to them under existing contractual agreements. When rejection rates increase, it can signal that carriers have better alternatives in the spot market or that available capacity is becoming more limited.
TRAFFIX reported a tender rejection rate of 12.9%, more than twice the 6.2% recorded during the same period a year earlier. Capacity constraints have been particularly noticeable in the refrigerated and flatbed segments.
Meanwhile, truckload volumes increased approximately 4.7% over the previous two weeks, indicating that seasonal shipping activity may be beginning to gain momentum.
This combination of stronger freight movement and limited truck availability could create additional upward pressure on transportation rates.
The timing is particularly important. The weeks leading up to the holidays typically bring increased demand for transportation as retailers, manufacturers, and distributors work to move products before major shopping events and year-end deadlines.
Stay Informed
Get freight market insights delivered to your inbox
Join industry professionals receiving our weekly analysis.
Retail replenishment, food and beverage deliveries, consumer goods, and temperature-controlled shipments all contribute to seasonal freight activity. For carriers, these additional shipping requirements can create more opportunities, especially in markets where available trucks are already limited.
If holiday freight volumes continue to increase without a corresponding improvement in capacity, carriers could gain even more negotiating power in the weeks ahead.
However, stronger rates do not automatically mean stronger profits. With diesel and maintenance expenses continuing to weigh on fleet budgets, carriers must carefully evaluate operating costs before accepting additional freight.
Rising Diesel Prices Continue to Pressure Carrier Profits
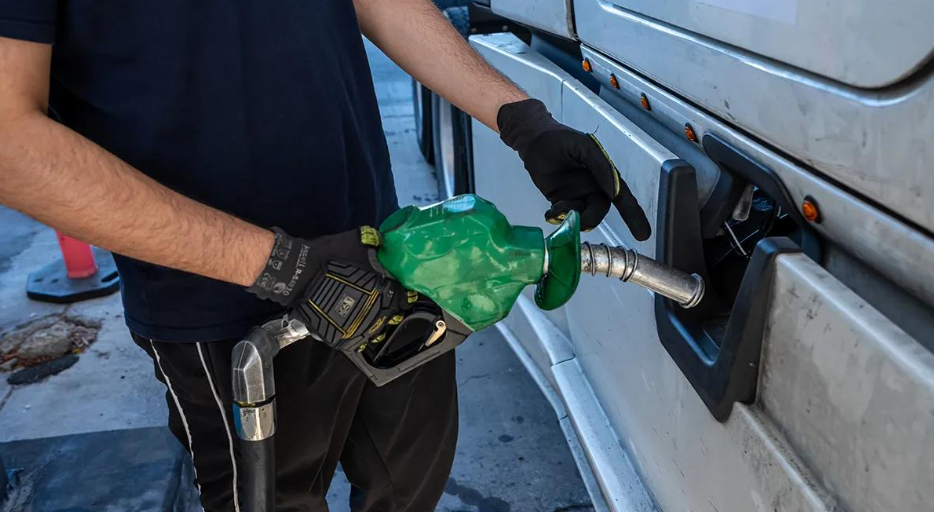
Although higher spot rates are encouraging for trucking companies, fuel expenses remain one of the industry's biggest financial challenges.
According to the U.S. Energy Information Administration (EIA), the national average on-highway diesel price stood at approximately $6.25 per gallon in October. That was slightly below September's $6.29 but roughly $2.60 higher than the October 2025 average.
DAT estimates that fuel accounted for approximately:
83 cents per mile for dry van spot rates.
91 cents per mile for refrigerated freight.
$1.00 per mile for flatbed freight.
These estimated fuel components were roughly twice as high as their year-earlier levels.
The impact on daily operations is significant. Consider a tractor-trailer covering 500 miles per day while averaging 6 miles per gallon. At October's estimated diesel price of $6.25 per gallon, its daily fuel expense would reach approximately $521.
By comparison, the same truck would have spent around $310 on fuel in February.
That difference illustrates how quickly higher diesel prices can absorb additional revenue generated by rising freight rates.
Fuel-Adjusted Rates Tell a Different Story
Looking beyond all-in spot rates provides a clearer picture of how much carriers are actually gaining from transportation pricing.
When the estimated fuel portion is removed, the remaining amount represents the linehaul rate, the compensation for transporting freight before fuel-related charges are included.
In October, average spot linehaul rates were:
Dry Van: $2.22 per mile, up 5 cents from September and 55 cents year over year.
Reefer: $2.69 per mile, down 1 cent from September.
Flatbed: $2.61 per mile, up 1 cent from September.
Although these rates remain above year-earlier levels, all three categories are still below their earlier peaks in 2026.
For example, dry van linehaul rates have declined 17 cents per mile since July, even as the estimated fuel component has increased by 21 cents.
This distinction matters because headline spot rates can make market conditions appear stronger than they are. Higher fuel-related charges do not necessarily translate into higher operating margins for carriers.
Fleet owners must account for more than diesel when calculating profitability. Driver wages, insurance premiums, equipment payments, repairs, tires, maintenance, and other expenses all influence how much revenue ultimately remains.
For smaller carriers and independent owner-operators, managing these costs is especially important because even modest changes in operating expenses can significantly affect cash flow.
Contract Freight Rates Continue to Set New Records
The upward movement in transportation pricing is not limited to the spot market. Contract freight rates also increased in October, with several equipment categories reaching record levels, according to DAT's latest data.
The average contract rates showed the following changes:
Dry Van: Increased 4 cents to $3.28 per mile, matching the previous record established in May 2022.
Refrigerated (Reefer): Reached $3.62 per mile, setting a new record for the second consecutive month.
Flatbed: Climbed to $4.05 per mile, marking its third consecutive monthly record.
Unlike spot rates, which are generally negotiated as all-in transportation prices, DAT's reported contract rates include fuel surcharges.
The continued increase in contract pricing suggests that tighter trucking capacity is beginning to influence longer-term transportation agreements as well.
For shippers and brokers, this could mean higher transportation budgets and greater competition for dependable carriers. Companies that rely heavily on contracted capacity may need to reassess their freight strategies, review existing agreements, and prepare for potentially higher transportation expenses.
For carriers, stronger contract rates can provide more predictable revenue and better planning opportunities. However, maintaining profitability will depend on securing fair pricing that reflects actual operating expenses and market conditions.
DAT also reported that during the first 10 months of 2026, average spot rates across all three equipment categories reached their highest levels for that period since the company's monthly records began in 2010.
What Comes Next for the Trucking Industry?
As the holiday shipping season progresses, the U.S. freight market is entering an important period that could determine how transportation rates develop heading into the end of the year.
The current situation presents an interesting contrast: freight demand has not experienced a major recovery, yet trucking rates are rising as available capacity continues to decline.
If seasonal shipping activity gains momentum while the number of available trucks remains limited, carriers could see further improvements in their negotiating position. Refrigerated and flatbed operators, in particular, may benefit from continued capacity constraints.
Nevertheless, the industry's financial outlook remains complicated. Elevated diesel prices, maintenance expenses, insurance costs, and other operating challenges continue to limit the benefits of higher freight rates.
For trucking companies, the priority will be finding the right balance between securing profitable loads, controlling operating expenses, and maintaining reliable service.
The key question heading into the final weeks of 2026 is whether holiday shipping demand will be strong enough to push an already tightening trucking market into an even more competitive environment.
One thing is becoming increasingly clear: even without a full recovery in freight demand, capacity is once again becoming a major factor in determining who has the upper hand in the trucking market.